

Revolut: Spend, Save, Trade
4.4

I judge a money app less by how many tools it puts on one screen than by how clearly it lets me see what is happening and decide what to do next. Revolut: Spend, Save, Trade brings everyday spending, savings goals and investing into one finance app, which can be convenient if you would rather not switch between several services. That convenience is also the main trade-off: putting different kinds of financial activity together asks you to be deliberate about which parts you use and what choices you make.
For a cautious user, I would start with the basic spending experience rather than treating the app as an all-in-one solution from day one. Get comfortable checking transactions and setting a budget before adding savings or trading to the routine. That gradual approach makes it easier to notice whether the layout and controls suit you, and helps keep investing decisions separate from the money you need for bills and ordinary purchases.
A useful fit, but not a universal replacement
I can see this being a good match for someone who likes to review day-to-day spending, keep a few savings goals visible and explore investing from the same app. It is less compelling if you only want a basic account from a provider you already use, or if you prefer to keep investments in a dedicated service with a narrower focus. An app can make access feel simple; that does not make every financial decision simple or suitable for everyone.
Compared with using a traditional banking app for payments and a separate savings or investment service, the appeal here is having fewer places to check. The downside is that a combined interface can encourage casual browsing between spending and higher-risk activities. I would use the convenience without letting it blur the difference between money for near-term needs and money I can afford to leave invested.
Trust starts with choices you can inspect
Revolut Ltd develops the app, which is free to download and rated for Everyone. It has an average rating of 4.4 from around 3.9 million ratings, alongside about 12,000 written reviews, and has been installed more than 50 million times. Those figures suggest that many people have tried it, but popularity is not a substitute for checking whether its tools and terms fit your circumstances.
The app first appeared on June 1, 2015, and version 10.119 is listed for devices running Android 9 or later. I would check the current app details and the options shown in my own account before relying on a particular workflow, since the experience can depend on the device and the account setup. When a financial app handles spending, savings and trading in one place, I think it is worth taking a few minutes to understand each area rather than tapping through setup automatically.
How I would keep control of the routine
For everyday use, I would make a small number of clear decisions first: which spending categories matter to me, what amount I want to set aside, and whether I want investing in my routine at all. A budget is most useful when its categories reflect real habits, not when I create so many that checking them becomes work. I would also review transactions regularly, so an unexpected item gets noticed while I still remember the purchase.
One practical habit is to treat savings goals as labels for separate priorities, such as travel or a replacement device, rather than as spare money that can be spent without thought. If round-ups are enabled, I would check how those small contributions fit with my cash flow. A feature that saves automatically can be helpful, but it is still worth confirming that the amount being moved aside does not make upcoming bills harder to cover.
There is a similar discipline to trading. I would learn how the relevant instrument works before placing an order, and I would not treat easy access or beginner-oriented explanations as a reason to invest. Prices can move against you, and trading is not a substitute for an emergency reserve. Someone who wants detailed analysis or a specialist investing interface may be better served by a dedicated platform, while a beginner who is not ready to accept market risk can simply leave that part unused.
First Impressions and Setup
So, I downloaded Revolut after hearing some buzz about it being the Swiss Army knife of financial apps. Setting it up was a breeze. The interface is sleek, minimalistic, and super intuitive. I felt like a pro navigating through it in no time. It's like the app was designed with people like me in mind—those who want to get straight to the point without any fuss.
That first impression matters, but I would not make a lasting trust judgment from a tidy home screen alone. For a money app, I want to know what I am authorizing, where I can review settings, and how to reach the relevant controls before I need them in a hurry. I would take the time to look through the account and security options available in the app, read prompts before granting access, and avoid assuming that a convenient sign-up flow means every later decision is equally straightforward.
Spending and Budgeting
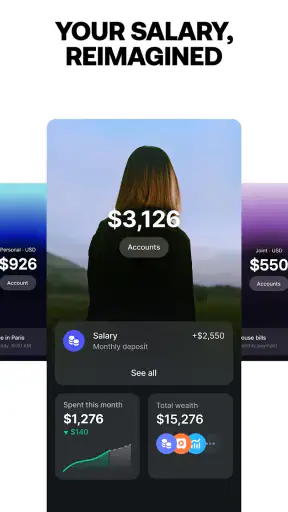
Now, let's talk about spending. We all love a little retail therapy, right? But keeping track of where your money goes can be a headache. This app makes it surprisingly easy. With real-time spending notifications, I felt like I had a personal accountant in my pocket. The budgeting feature is also pretty neat. It lets you set monthly limits for different categories. I set mine for groceries, eating out, and entertainment, and it’s been a game-changer. No more nasty surprises at the end of the month!
A realistic way I would use those tools is to check a notification after a grocery run, then compare the transaction with the category I planned for the month. If the total is higher than I expected, the useful next step is not to blame the app or blindly cut the next budget; it is to look at what actually changed. Notifications can make spending visible quickly, while category limits give that information context. Neither replaces checking that a transaction is correct or deciding whether a purchase was worthwhile.
I would keep the category setup modest at first. A few broad categories are easier to review consistently than a long list that demands constant maintenance. If a purchase appears in a category that does not make sense, I would use that as a prompt to review how I am organizing my budget rather than treating the monthly limit as a precise forecast. The feature is most helpful as a guide for noticing patterns, not as a guarantee that spending will stay within a chosen amount.
This is where the app can differ from a basic bank app that mainly shows balances and transaction history: the budgeting layer can turn a list of purchases into a routine for checking habits. But someone who already tracks every expense in a spreadsheet may find a second system unnecessary. I would choose one method I can keep up with, rather than entering the same spending in multiple places and creating more work than insight.
Savings Made Simple
Saving money has always felt like a chore to me, but Revolut turns it into a bit of a game. You can create different "vaults" for various savings goals. Want a new laptop or planning a vacation? Just set up a vault and watch your savings grow. What's even cooler is the "round-up" feature, where it rounds up your spare change from purchases and adds it to your savings. It's like saving on autopilot!
For a goal with a deadline, I would pair a vault with a realistic target and check progress against the time remaining. That makes the feature more actionable than simply naming a pot of money. I would also distinguish goals I may need soon from longer-term plans, so a tempting balance does not create the impression that all saved money is immediately available for optional spending.
Round-ups are best understood as a small habit builder, not a complete savings plan. They can add up gradually, but the amount depends on what I spend, so I would not rely on them alone for a known upcoming cost. If my budget is tight, I would review whether automatic contributions still make sense before enabling them. The convenience is real, but any automatic movement of money deserves occasional attention.
This approach suits people who benefit from visible, named goals. If you prefer one simple savings balance or want to compare interest terms across providers, a separate savings account may be a better fit for that specific job. I would compare the terms that apply to my account before deciding where to keep money, and avoid assuming that a goal-tracking feature itself determines what return or access conditions apply.
Trading for Everyone
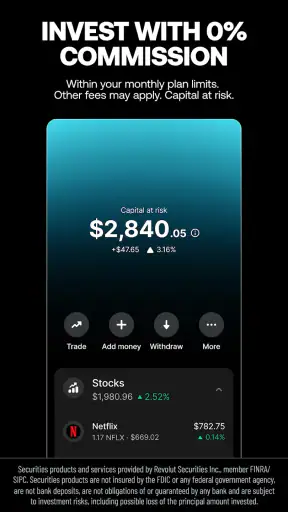
Okay, I’ll admit—trading has always sounded intimidating to me. But this app breaks it down into bite-sized pieces. You can start trading stocks and cryptocurrencies with just a few taps. The educational resources within the app are a lifesaver, especially if you're a newbie like me. Plus, the trading fees are quite reasonable, which is a bonus.
The low-friction path from reading about an asset to placing an order is exactly why I would set a personal pause before trading. I would first decide what I am trying to learn, research the risks of the asset, and only then consider whether an order makes sense. Beginner-friendly explanations can help with vocabulary, but they are not personal financial advice and cannot tell me whether a particular investment suits my situation.
I would also separate trading money from the cash I rely on for rent, bills and near-term plans. Stocks and cryptocurrencies can behave very differently, and neither should be approached as a quick fix for a savings shortfall. Someone seeking advanced tools, extensive research or a specialist investing workflow may find a dedicated broker more appropriate. Someone who does not want the possibility of losses can use the spending and savings parts without making trading part of their routine.
Before making any trade, I would read the current terms and costs shown for the instrument and account I am using. Costs and conditions matter even when an interface makes an order feel simple. I would not assume that one description of fees applies identically to every product or circumstance; checking the details at the point of decision is a more useful habit than relying on a broad impression.
Security and Support
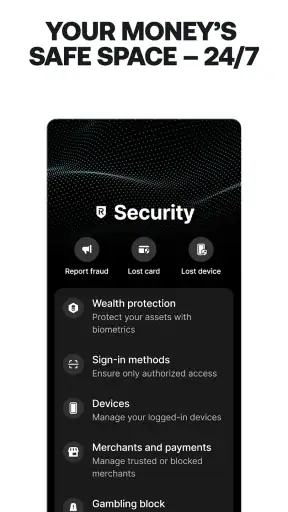
In today’s world, security is a big deal, and Revolut takes it seriously. The app uses top-notch security measures to keep your data safe. I was impressed by the additional features like disposable virtual cards for online shopping. It’s like having a bodyguard for your money. And if you ever run into issues, their customer support is just a chat away—super responsive and helpful.
I would be more careful about the scope of what I claim here: security is not something I can judge from a reassuring design or a single tool. A disposable virtual card can be useful for a particular online purchase when I want to avoid reusing the same card details, but it does not remove the need to check the merchant, review the transaction and protect access to the account itself. I would treat it as one choice in a safer purchasing routine, not as a guarantee against every kind of fraud or data exposure.
When the app asks for information or access, I would pause to consider whether the request makes sense for the action I am taking. I would review privacy and account settings in the app and make choices deliberately instead of granting access simply to clear a prompt. If I have a concern about how information is used, I would look for the relevant explanation and controls before proceeding. That is a better basis for trust than guessing about permissions or assuming that every account has identical options.
Support through chat can be convenient when I need help without switching channels, but I would still keep a record of the issue and read any instructions carefully, especially when money or account access is involved. If a problem is urgent, I would use the support route presented in the app and avoid sharing sensitive details outside the service. My trust depends not only on whether help is available, but also on my own habit of using the intended channel and checking what I am being asked to do.
Final Thoughts
All in all, Revolut: Spend, Save, Trade feels like the financial app I didn’t know I needed until I started using it. It's versatile, user-friendly, and packed with features that make managing money less of a chore and more of an experience. Whether you're a budgeting novice or a trading enthusiast, there’s something here for everyone. Give it a whirl and see how it transforms your financial life!
My recommendation is more measured: I would try it if the attraction of bringing spending, saving goals and trading together matches how I actually manage money, then keep only the tools I find useful. I would not choose it solely because it has a large audience, nor assume that a single app is automatically better than a bank app plus a specialist savings or investment service. For a careful user, the strongest approach is to set up the parts that support everyday decisions, review the choices that affect money or personal information, and leave the rest alone until there is a clear reason to use it.
4.4
11.58K Reviews
Pros
- User-friendly interface for seamless navigation.
- Instant notifications for every transaction.
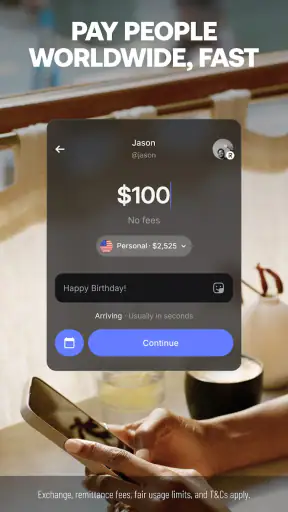
- Supports multiple currencies for global use.
- Offers virtual cards for secure online shopping.
- Fee-free international transfers save money.
Cons
- Limited customer support options available.
- Certain features require premium subscription.
- Not all countries supported for full features.
- Some users report app crashes occasionally.
- Exchange rates may vary
- affecting users.


